Key Takeaways
- IPO subscription is divided into three distinct buckets: QIB, NII, and Retail, each with its own participation rules.
- Understanding these quotas is vital because they dictate how shares are distributed when an IPO is oversubscribed.
- Retail quotas are often protected from institutional bidding, but oversubscription leads to proportionate allotment processes.
- Institutional interest (QIB) is often viewed as a proxy for 'smart money' confidence in the company's valuation.
The Mechanics of IPO Subscription
When a company goes public in India, it doesn't just open a single 'book' for all investors. To ensure a fair distribution of equity and market stability, SEBI mandates that the public offer be split into specific categories. Understanding the QIB, NII, and Retail quotas is the first step for any retail investor looking to move beyond simple 'listing day' speculation.
Defining the Categories
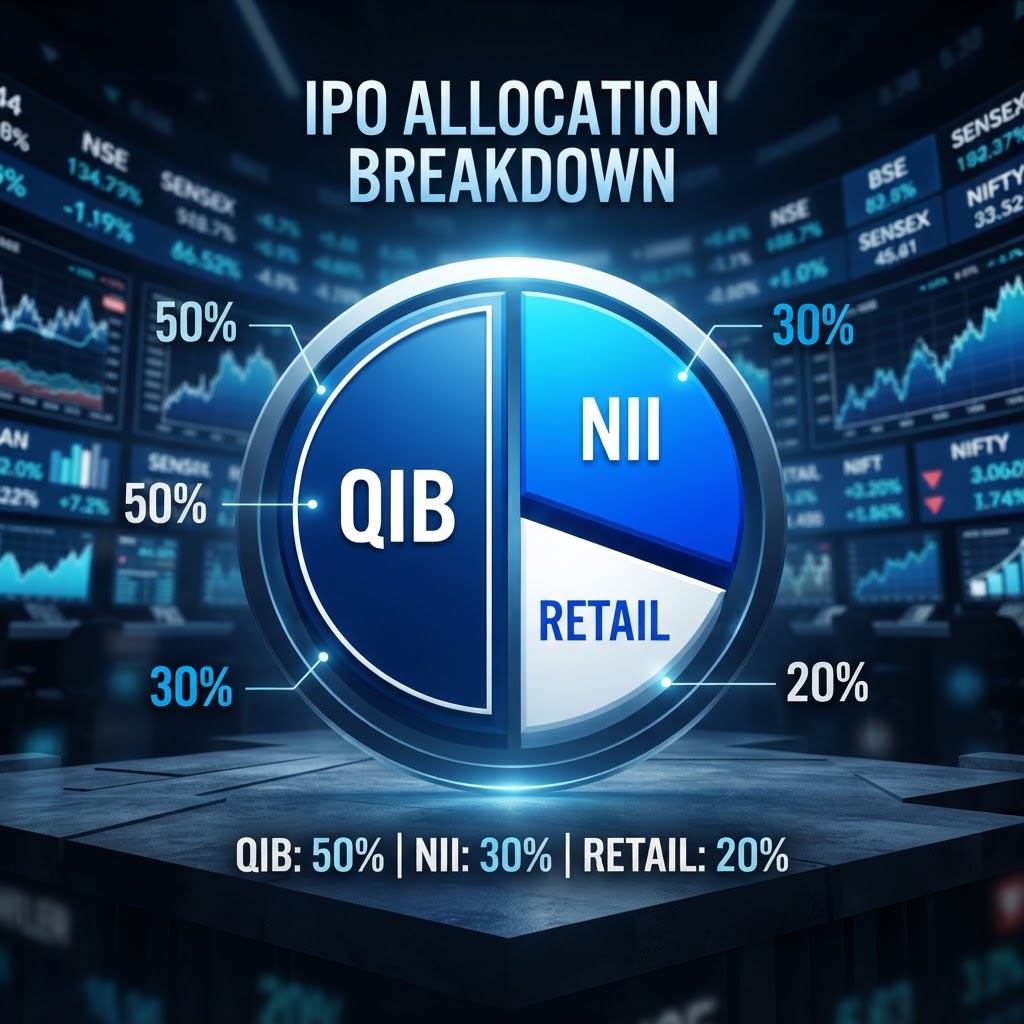
Qualified Institutional Buyers (QIBs): These are the 'heavy hitters' of the market—commercial banks, mutual funds, insurance companies, and foreign portfolio investors (FPIs). Because they possess the resources for deep fundamental research, they are typically allocated a significant portion of the IPO, often 50% or more. Their subscription levels are closely watched by retail investors as a signal of institutional conviction.
Non-Institutional Investors (NIIs): Also known as High Net-worth Individuals (HNIs), this bucket includes resident Indians, Hindu Undivided Families (HUFs), and companies investing over ₹2 lakh. While they lack the institutional status of QIBs, they provide significant liquidity to the IPO process.
Retail Individual Investors (RIIs): This is the segment for the common investor—those who apply for shares worth up to ₹2 lakh. SEBI reserves a specific portion of the IPO for this category to ensure that retail participation is not crowded out by massive institutional orders.
Why the Quotas Matter
Why does this split exist? If all shares were open to everyone, institutional buyers would almost certainly dominate the book due to their sheer capital volume, effectively squeezing out the individual investor. By carving out a protected Retail quota, the regulator ensures that the public can participate in the growth of new firms.
However, the 'Quota' is not just about protection; it is about how shares are allotted during oversubscription. When an IPO is oversubscribed, allotment is not decided on a first-come, first-served basis. For retail investors, if the demand exceeds the supply in the retail category, the process moves to a lottery or proportionate basis. This is why you may often receive zero shares in a 'hot' IPO despite having paid your application money.
The Bigger Picture: Institutional Signals
Investors often look at the QIB subscription percentage as a barometer for the IPO's success. High QIB interest suggests that seasoned fund managers have analyzed the company's financials and deem the valuation attractive. Conversely, a lukewarm QIB response can sometimes act as a cautionary signal, even if the retail category is heavily oversubscribed due to market sentiment or brand recognition.
What to Watch Next
As you evaluate upcoming IPOs, focus less on the absolute subscription numbers and more on the composition of those subscriptions. Are the QIBs interested? Is the retail category being 'over-flooded' due to listing gain speculation, or is it steady interest? Understanding these dynamics allows you to filter the signal from the noise, helping you make decisions based on the structural reality of the market rather than hype.
⚠️ Disclaimer: IndiaMarketInsights.com is NOT a SEBI-registered Investment Adviser, Research Analyst, or Investment Advisory firm. This article is published for educational and informational purposes only and does not constitute investment advice, an offer to buy or sell, or a recommendation of any security or financial product. All data and information referenced is sourced from publicly available news and filings. Please consult a SEBI-registered investment advisor before making any investment decision. Past performance is not indicative of future results. Investing in securities involves risk, including possible loss of principal.